Retirement should be a time to enjoy the life you've worked hard to build. But with the rising costs of groceries, housing, health care, insurance, travel, and everyday expenses, many retirees are looking for practical ways to make their money go further.
The good news is that stretching your retirement income doesn't always require major lifestyle changes. Small adjustments, taking advantage of benefits you've earned, and simply asking about senior or veteran discounts can add up to meaningful savings over the course of a year.
For even more ideas, AMAC offers these Practical Ways for Seniors to Save Money.
Here are some other places to start.
1. Ask for the Senior Discount — Even If It Isn't Advertised
One of the easiest ways to save is also one of the most overlooked: ask if a senior discount is available.
There is no universal age when you become eligible for senior discounts. Some businesses begin offering them at 50 or 55, while others set the minimum age at 60, 62, or 65. Discounts can also vary by location.
Before paying at a restaurant, hotel, store, attraction, or service provider, simply ask:
"Do you offer a senior discount?"
You may be surprised by the answer.
A regularly updated list of discounts can be found at SeniorLiving.org's Senior Discount Guide. Discounts and eligibility requirements can change, so always confirm the offer before making a purchase.
Senior Discounts You May Not Know About
Walgreens — Age 55+
Walgreens offers a monthly Seniors Day for myWalgreens members age 55 and older. Eligible shoppers may receive discounts on qualifying regular-priced merchandise. Restrictions apply, and offers can change.
Learn more about Walgreens Seniors Day.
Ross Dress for Less — Age 55+
Ross offers a 10% discount on Tuesdays to customers age 55 and older. Shoppers should tell the associate they qualify before completing their purchase, and identification may be requested.
Check the Ross Stores website or ask your local store for current details.
Amtrak — Age 65+
Traveling by train? Amtrak passengers age 65 and older can receive 10% off most rail fares on most Amtrak trains. Restrictions apply.
Learn more about the Amtrak Senior Discount.
Marriott — Age 62+
Marriott offers special senior rates for travelers age 62 and older at participating properties. Availability and the amount saved can vary, so compare the senior rate with other available promotions before booking.
Search Marriott Senior Discounts.
National Parks — Age 62+
This may be one of the best senior travel bargains available.
U.S. citizens and permanent residents age 62 and older can purchase an America the Beautiful Senior Annual Pass for $20 or a Senior Lifetime Pass for $80. The pass provides access to participating federal recreation sites and may also provide discounts on certain amenities such as camping.
Learn more about the National Park Service Senior Pass.
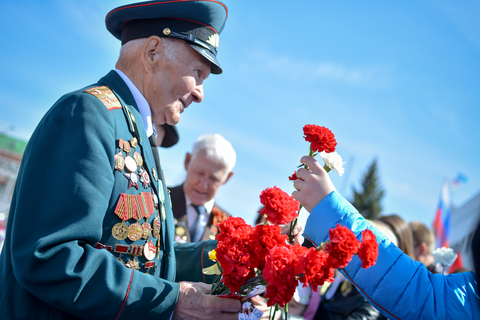
2. Veterans: Don't Overlook These Savings
If you served in the U.S. military, your veteran status may open the door to additional savings that can help stretch your retirement income. Some benefits are broadly available to veterans, while others depend on disability rating, discharge status, income, or other eligibility requirements.
Free Lifetime National Parks Pass for Veterans
Here's a great benefit that many veterans may not realize they have: U.S. military veterans are eligible for a free Military Lifetime Pass to national parks and other participating federal recreation lands.
The pass covers entrance or standard day-use fees at sites managed by agencies including the National Park Service, U.S. Fish & Wildlife Service, U.S. Forest Service, Bureau of Land Management, Bureau of Reclamation, and U.S. Army Corps of Engineers.
Learn more about the Free Lifetime Military Pass for Veterans from the National Park Service.
Commissary and Military Exchange Shopping
Eligible veterans may be able to shop at military commissaries and exchanges, potentially providing another way to save on groceries, household products, clothing, electronics, and other purchases.
Check your eligibility through the U.S. Department of Veterans Affairs' Commissary and Exchange Privileges guide.
You can also visit the Defense Commissary Agency to find commissary locations, sales information, and shopping resources.
Check Your VA Benefits — Even If You Haven't Looked in Years
Veterans shouldn't assume they're receiving every benefit for which they may qualify.
Depending on a veteran's circumstances, benefits may include health care and prescription assistance, travel reimbursement for certain VA medical appointments, VA home loan benefits, disability compensation, pension benefits, burial benefits, and additional benefits for eligible dependents.
Start at VA.gov to review available benefits and eligibility requirements.
The VA also provides a Veteran Benefit Eligibility Matrix, which outlines additional benefits that may be available based on VA disability ratings and individual circumstances.
Ask About Veteran Discounts Everywhere You Shop
Many private businesses offer military or veteran discounts on hotels and travel, restaurants, cell phone plans, home improvement purchases, auto services, entertainment, retail purchases, and insurance.
These discounts aren't always advertised. Ask:
"Do you offer a veteran or military discount?"
If you're both a senior and a veteran, check both discounts before paying and determine which provides the greater savings.
3. Look Beyond Discounts — Search for Benefits You Already Qualify For
Saving 10% at a restaurant is nice, but some government and community programs can potentially save eligible retirees much more.
Depending on your income, resources, age, and where you live, assistance may be available for health care, prescription drugs, utilities, food, transportation, housing, and other expenses.
Don't automatically assume your income is too high to qualify. Eligibility requirements vary among programs.
4. Check for Medicare Savings Programs
Health care can consume a significant portion of a retirement budget. Some Medicare beneficiaries may qualify for a Medicare Savings Program, which can help pay Medicare Part A and Part B premiums. Depending on the program, assistance may also cover deductibles, coinsurance, and copayments.
Visit Medicare.gov's Medicare Savings Programs to learn more.
Medicare mistakes can also become expensive. AMAC regularly publishes information about enrollment, coverage and costs in its Medicare section, including information designed to help older Americans better understand their Medicare choices.
5. See If You Qualify for Extra Help With Prescription Costs
Medicare's Extra Help program assists qualifying people with limited income and resources with Medicare Part D prescription drug costs, including premiums, deductibles and coinsurance.
Eligibility limits can change annually, so check the current requirements before assuming you do or don't qualify.
Visit Medicare.gov — Extra Help for current information.
6. Check Your Phone and Internet Bills
Your monthly phone or internet bill may offer another opportunity to save.
The federal Lifeline program provides eligible low-income consumers with a monthly discount on qualifying phone or internet service.
Find current eligibility information at LifelineSupport.org.
While you're at it, call your internet, cell phone, cable, insurance, and other service providers. Ask whether you're on their lowest-cost plan and whether they offer senior, veteran, loyalty, paperless billing, autopay, or bundled-service discounts.
7. Investigate Property Tax Relief
If you own your home, don't overlook property taxes.
Many states and local governments have programs for older homeowners that can include exemptions, assessment freezes, credits, deferrals, or other forms of property-tax relief. Veterans, particularly veterans with service-connected disabilities, may qualify for additional exemptions in some states.
Contact your county property appraiser, assessor, or tax office and ask:
- Are there additional exemptions for residents age 65 or older?
- Are there income-based exemptions?
- Is there a property-tax freeze or limitation program?
- Are there special property-tax exemptions for veterans?
- Are additional benefits available to veterans with service-connected disabilities or surviving spouses?
A single tax exemption could potentially save more than collecting dozens of small retail discounts.
8. Take Advantage of Free Tax Preparation
Why pay for tax preparation if you qualify for reputable free assistance?
The IRS's Tax Counseling for the Elderly (TCE) program provides free tax help, particularly for people age 60 and older. The Volunteer Income Tax Assistance (VITA) program also provides free assistance to qualifying taxpayers.
AARP Foundation Tax-Aide also provides free tax preparation assistance at thousands of locations during tax season.
Find information through the IRS Free Tax Preparation Programs.
9. Review Your Recurring Expenses Once a Year
Automatic payments are convenient, but they also make it easy to forget what you're paying for.
At least once a year, review your bank and credit card statements for recurring expenses such as:
- Streaming services
- Gym memberships
- Subscription boxes
- Apps and software
- Cable and internet packages
- Cell phone plans
- Insurance policies
- Memberships you no longer use
Canceling even $50 in unnecessary monthly expenses saves $600 a year.
Also shop your auto and homeowners insurance periodically. Ask about low-mileage, safe-driver, multi-policy, home-security, defensive-driving, mature-driver, and veteran discounts.
For additional ideas, read AMAC's Practical Ways for Seniors to Save Money, which covers budgeting, reducing expenses, shopping smarter, and other strategies for seniors living on a fixed income.
10. Make Your Grocery Budget Work Harder
Food is another area where small changes can produce noticeable savings.
Build meals around weekly sales, use store loyalty programs and digital coupons, buy store brands when the quality is comparable, and freeze food before it goes to waste.
Many supermarkets also have senior discount days, but these programs vary greatly by location. Ask your local grocery store whether it offers a senior day or other age-based savings.
Veterans who have commissary privileges should also compare commissary prices with their local supermarkets and warehouse clubs to determine where they're getting the best overall value.
And don't forget restaurant discounts. Some national chains and many locally owned restaurants offer reduced prices, senior menus, military discounts, free beverages, or other specials — but you may have to ask.
11. Use Your Library for More Than Books
Your local library may be one of the best free resources in your community.
Depending on the library system, your library card may provide access to e-books, audiobooks, movies, newspapers, magazines, educational courses, genealogy resources, computers, Wi-Fi, community programs, and even passes to local museums and attractions.
Before purchasing another subscription, check whether your library already provides it for free.
12. Be Strategic About Social Security and Retirement Withdrawals
Stretching retirement income isn't only about spending less. It's also about making informed decisions about the income you already have.
Social Security claiming decisions, retirement-account withdrawals, taxes, required minimum distributions, and Medicare premiums can interact in ways that aren't always obvious.
Social Security is also one area where getting reliable information before making a decision can be especially important.
The AMAC Foundation provides free, personalized Social Security guidance through nationally accredited Social Security Advisors. The service is available to AMAC members and the public, with no charge or product to purchase. If you have questions about when to claim, spousal or survivor benefits, working while receiving benefits, or other Social Security rules, visit the AMAC Foundation Social Security Advisory Service.
Readers can also explore the latest AMAC Social Security articles and Ask Rusty columns for answers to common retirement and Social Security questions.
Don't Let Medicare Timing Create an Expensive HSA Mistake
If you're approaching Medicare eligibility and still contributing to a Health Savings Account (HSA), timing matters. Medicare enrollment can affect your ability to continue making HSA contributions, and mistakes can potentially result in tax penalties.
AMAC Foundation explains the issue in Don't Let Medicare Cost You Your HSA Tax Benefits.
People who continue working after age 65 may also want to read I'll Be 65 Soon and am Working, Must I Enroll in Medicare? — Ask Rusty.
Look at Your Entire Retirement Picture
Making your retirement income last involves more than finding discounts. Budgeting, taxes, Social Security, Medicare, retirement accounts, investments, and withdrawal strategies can all affect how much money you have available each month.
AMAC's article Build Your Financial Muscle: Beyond Social Security and Medicare offers additional ideas for strengthening your financial position in retirement.
Small Savings Can Become Big Savings
Saving $5 or $10 at a time may not sound significant. But retirement can last 20, 30, or more years, and recurring savings add up.
A $25 monthly reduction in your cell phone bill saves $300 a year. Cutting $50 in unused subscriptions saves $600 a year. Add senior or veteran discounts on groceries, travel, restaurants, pharmacies, hotels, and entertainment, and the savings can become substantial.
The biggest lesson may be the simplest:
Don't be afraid to ask, "Do you offer a senior or veteran discount?"
Then take it one step further and ask:
"Is there another program that could save me money?"
You spent decades earning your retirement. Taking advantage of discounts, benefits, and programs for which you're eligible isn't about being cheap — it's about making your retirement dollars work harder.
Discounts, prices, eligibility requirements, and government program limits can change. Check directly with the business, government agency, or program before making financial decisions.